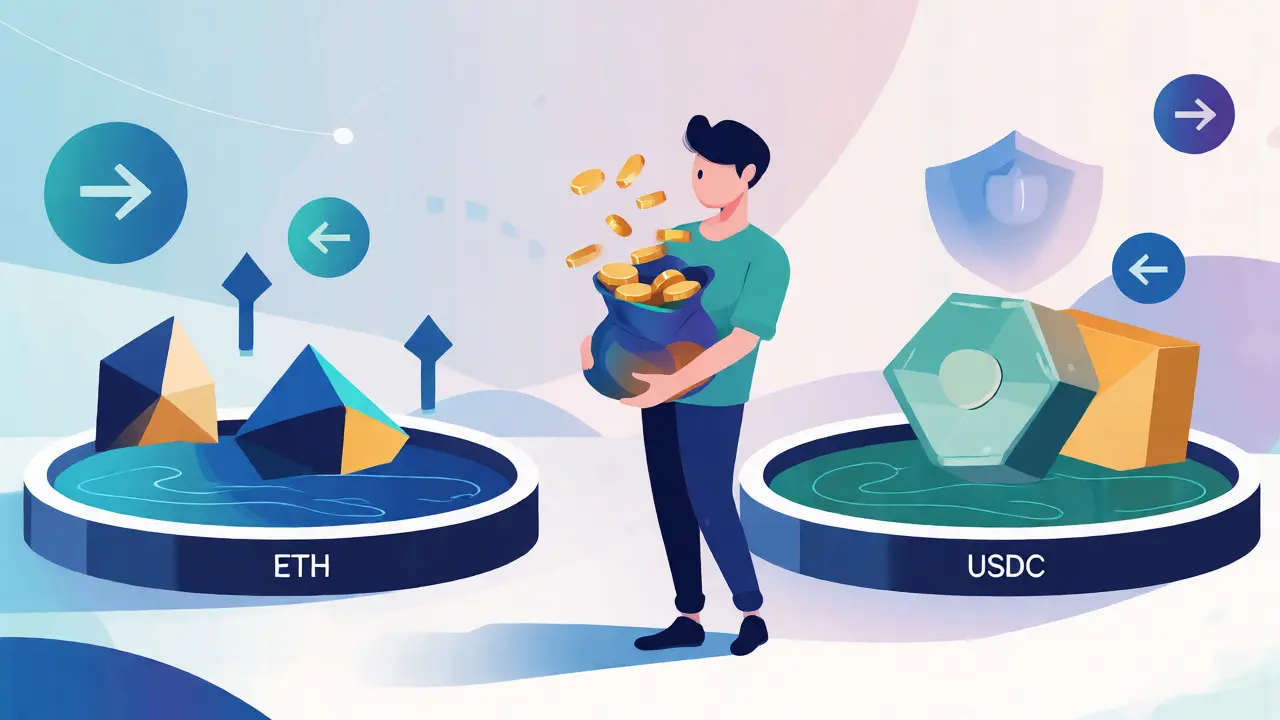
You deposited your ETH and USDC into a Uniswap pool, expecting to earn trading fees. A month later, you pull out your funds only to find that if you had just held the tokens in your wallet, you would have been richer. This frustrating scenario is known as Impermanent Loss, a phenomenon where the value of assets provided to an Automated Market Maker (AMM) diverges from their value if held separately. It’s not actually "impermanent" unless prices return to their starting point, which they often don’t. For liquidity providers (LPs), this silent leak can eat away profits faster than fees can generate them. The good news? You can hedge against it.
What Is Impermanent Loss Really?
Before we fix it, let’s break it down simply. When you provide liquidity to an AMM like Uniswap, you deposit two tokens in a specific ratio, usually 50/50. As traders buy one token and sell the other, the pool rebalances itself. If Token A skyrockets in price, arbitrage bots will sell more of it into the pool to keep the price aligned with external markets. Consequently, your share of the pool ends up containing less of the winning token and more of the losing one compared to when you started.
The math is unforgiving but predictable. In a standard 50/50 pool, if the price of one asset doubles relative to the other, you suffer a 5.7% impermanent loss compared to holding. If the price quadruples, that loss jumps to nearly 41%. These numbers assume no fees are earned. In reality, high trading volume can offset these losses, but during low-volume periods or extreme volatility, the pain is real.
| Price Ratio Change | Impermanent Loss % | Scenario Example |
|---|---|---|
| 1.25x | ~0.6% | Mild volatility, negligible impact |
| 1.50x | ~2.0% | Noticeable underperformance vs HODL |
| 2.00x | ~5.7% | Significant loss if fees are low |
| 3.00x | ~15.5% | Major deviation, requires strong fees |
| 4.00x | ~41.4% | Critical exposure, high risk |
Strategy 1: Choose Your Pairs Wisely
The easiest way to minimize impermanent loss is to pick pairs that move together. Stablecoin pairs like USDC/USDT or DAI/USDC are popular because their prices rarely diverge significantly. Since both assets are pegged to the dollar, the price ratio stays near 1:1, meaning impermanent loss is virtually zero. You still earn trading fees, albeit at lower rates due to high competition among LPs.
If you want higher yields, look for correlated assets. For example, pairing ETH with Lido Staked ETH (stETH) or wrapped BTC (WBTC) with Bitcoin reduces divergence risk. While not perfectly stable, these assets maintain a tight correlation, limiting the potential for large price gaps that trigger severe impermanent loss.
Strategy 2: Direct Hedging via Spot Markets
For those willing to put in the work, direct hedging involves taking an opposing position on a centralized exchange (CEX) or another DeFi platform. If you are providing liquidity for ETH/USDC, you might short ETH on a futures market. If ETH rises, your spot holdings in the pool lose value relative to holding, but your short position gains profit, offsetting the loss.
This method requires active monitoring. You need to rebalance your hedge as the price moves. If ETH drops, your short position loses money, but your LP position retains more ETH, balancing the portfolio. Tools like Zapper or DeBank help track these positions, but gas fees on Ethereum mainnet can make frequent rebalancing expensive. Layer 2 networks like Arbitrum or Optimism offer cheaper transactions, making this strategy more viable for smaller accounts.
Strategy 3: Leverage Impermanent Loss Protection Protocols
Some protocols build insurance directly into their smart contracts. Bancor pioneered this approach with its IL protection mechanism. Initially, Bancor offered full coverage after 100 days of holding liquidity. Recent updates have modified this, but the concept remains: the protocol uses part of the trading fees to compensate LPs for impermanent loss over time.
Other newer protocols use oracle data to calculate losses dynamically and pay out claims automatically. While convenient, these protections often come with trade-offs, such as lower base APRs or lock-up periods. Always check the current terms, as many early projects scaled back their guarantees due to unsustainable payouts during extreme market swings.
Strategy 4: Options and Derivatives
Advanced users can use options to create synthetic hedges. Buying protective puts on the underlying assets limits downside risk. For instance, if you hold an ETH/USDC pair, buying put options on ETH protects against a sharp decline. Conversely, covered calls can generate extra income to offset potential losses from price appreciation.
Platforms like Lyra or Dopex offer decentralized options markets. However, options pricing includes premiums that reduce net returns. This strategy works best when implied volatility is high, allowing you to sell expensive options or buy cheap protection. It demands a solid understanding of Greeks (Delta, Theta, etc.) and isn’t suitable for beginners.
Strategy 5: Automated Range Management
With the rise of concentrated liquidity in Uniswap v3 and v4, managing price ranges became critical. If your liquidity range is too narrow, you get pushed out of the pool during volatility, missing fees and realizing losses. Automated vaults, such as those provided by Gamma Strategies or Arrakis Finance, manage these ranges for you. They programmatically adjust your position to stay within profitable zones, effectively automating the hedging process.
These tools use algorithms to predict optimal ranges based on historical volatility. While they charge performance fees, they save hours of manual labor and often outperform static strategies. Account abstraction standards like ERC-7702 are further enabling smart contract wallets to execute complex hedging logic without user intervention, signaling a shift toward fully autonomous liquidity management.
Practical Tips for Implementation
- Start Small: Test your hedging strategy with a small amount before committing significant capital. Gas fees and slippage can erode profits quickly.
- Monitor Correlation: Use tools to check the historical correlation between paired assets. High correlation equals low impermanent loss risk.
- Factor in Fees: Calculate if the trading fees generated by the pool exceed the cost of your hedge. If not, the strategy is inefficient.
- Use Layer 2s: Deploy on Arbitrum, Base, or Polygon to reduce transaction costs associated with rebalancing hedges.
- Diversify: Don’t put all your eggs in one basket. Spread liquidity across multiple pools with different risk profiles.
Frequently Asked Questions
Is impermanent loss permanent?
Not necessarily. It is called "impermanent" because if the price ratio of the paired assets returns to the level it was at when you entered the pool, the loss disappears. However, if you withdraw your liquidity while prices are divergent, the loss becomes realized and permanent.
Can trading fees eliminate impermanent loss?
Yes, if the trading fees generated by the pool are high enough. In highly volatile markets with heavy trading volume, the accumulated fees can outweigh the impermanent loss, resulting in a net positive return compared to holding.
Which pairs have the lowest impermanent loss?
Stablecoin pairs (e.g., USDC/USDT) have the lowest impermanent loss because their prices remain pegged. Correlated assets like ETH/stETH also exhibit minimal divergence compared to uncorrelated pairs like ETH/DOGE.
Do I need technical skills to hedge impermanent loss?
Basic strategies like choosing stablecoin pairs require little technical skill. Advanced methods like options hedging or automated range management require understanding derivatives, smart contracts, and market dynamics.
How does Uniswap v3 affect impermanent loss?
Uniswap v3 allows concentrated liquidity, which increases capital efficiency and fee earnings but also amplifies impermanent loss risk. If the price moves outside your selected range, you end up holding 100% of the depreciating asset, maximizing the loss.